Gippsland First Home Buyers in 2026: A Post-October 2025 Playbook
This is a follow-up to our earlier First Home Buyer Gippsland 2026 explainer — it tracks the structural changes that took effect on 1 October 2025 and the Gippsland-specific buyer behaviour through 2026.
The Gippsland first home buyer landscape shifted on 1 October 2025 and most buyers in the region still haven’t fully adjusted their playbook. The Federal Government’s expanded First Home Guarantee — now operating as the 5% Deposit Scheme — removed income caps, lifted place limits and reset property price caps across regional Victoria. On top of that, the Victorian State Revenue Office continues to pay the flat $10,000 First Home Owner Grant (FHOG) for new builds and substantially renovated homes, and the stamp duty exemption sits at $750,000. The headline numbers are bigger and broader than at any point in the scheme’s history, but the cap structure still channels Gippsland first home buyers into a narrow band of the regional market. This post walks through how the stacking works in practice, where the new caps leave room for a deposit-only purchase, and which Gippsland sub-markets are absorbing the most first home buyer demand in 2026.
What actually changed on 1 October 2025
The old First Home Loan Deposit Scheme had three narrow windows: a $125,000 individual income cap, a $200,000 joint income cap, and a hard quota of places per financial year. Buyers who missed the quota window often waited twelve months for the next release, and couples earning above $200,000 were excluded entirely even if they had a $50,000 deposit ready. The October 2025 expansion removed both income caps and uncapped the number of places. For Gippsland, the more consequential change was the regional property price cap, which jumped to $1.5 million from the previous $900,000. That single number — $1.5 million — is now well above the regional median, which means the cap no longer constrains almost any buyer who can service a regional mortgage in the first place.
The state-level support layer sits separately. The Victorian $10,000 FHOG applies only to newly built or substantially renovated homes valued up to $750,000, and the stamp duty exemption runs from $0 to $750,000 with a tapered concession above that. Critically, the FHOG is the only piece that requires a new build — the 5% Deposit Scheme can be used on any eligible home inside the price cap, established or new.
How the stacking actually plays out for a $480,000 new build
Take a Warragul or Traralgon first home buyer buying a $480,000 new house-and-land package from a volume builder in 2026. The deposit required under the 5% scheme is $24,000 — plus typical establishment costs of another $8,000 to $12,000, taking total cash needed to settlement to roughly $32,000 to $36,000. Lenders’ mortgage insurance (LMI) is waived because the government guarantee covers the gap between the 5% deposit and the 20% threshold. The FHOG contributes $10,000 post-completion of the build, and the stamp duty saving on a $480,000 purchase in regional Victoria runs roughly $21,000 in 2026 — together about $31,000 in state support. Net cash outlay to settle, before considering the post-completion FHOG reimbursement, is effectively in the $5,000 to $10,000 range, which is the lowest first home buyer entry cost Gippsland has ever seen.
The same arithmetic does not work above $650,000, where the LMI hurdle returns because the regional price cap for the no-LMI benefit is $650,000 under the 5% Deposit Scheme. The new headline $1.5 million cap applies to the scheme eligibility, but the practical no-LMI benefit still ends at $650,000 for regional Victoria. Buyers between $650,000 and $1.5 million can still use the 5% deposit structure, but lenders will require mortgage insurance on the borrowing above 80% loan-to-value, which materially changes the cost equation. Above $750,000, the FHOG falls away and the stamp duty concession tapers.
What the Gippsland numbers are showing
The Latrobe-Gippsland SA4 region recorded the strongest quarterly median price movement in regional Victoria through 2025, with regional Victoria’s overall median reaching $636,500 — a record high for the area. Within the SA4, Traralgon and Warragul are leading the price tier at the $480,000 to $550,000 mark, while Sale and Maffra sit in the $420,000 to $490,000 corridor. East Gippsland is more stratified: Bairnsdale established housing in the $380,000 to $460,000 range, Paynesville waterfront well above, and the Nicholson 3882 corridor now offering covenant dream-home blocks from $229,500 vacant and house-and-land packages from $668,000 to $698,000.
According to reporting from the Latrobe Valley Express, more than 600 Gippslanders had used the expanded federal scheme within the first quarter of the rollout, a take-up rate that outpaced every other regional SA4 in Victoria. The buyers were heavily concentrated in Warragul, Traralgon, Sale and the East Gippsland coastal corridor — the towns where the median sits inside both the FHOG cap and the no-LMI threshold.
The Nicholson build angle: covenant blocks vs house-and-land packages
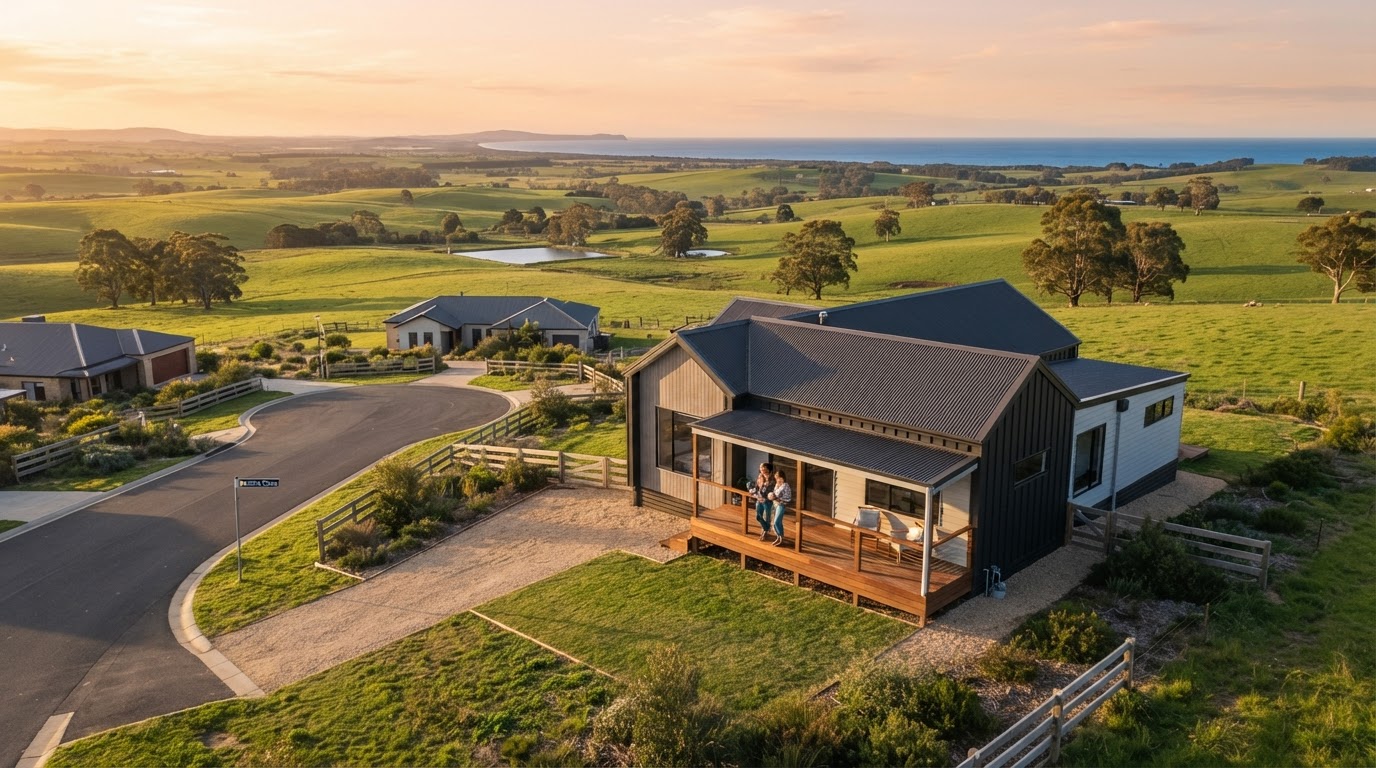
The October 2025 changes have a specific effect on the Nicholson 3882 build pipeline that first home buyers should understand. Under the old cap structure, a Nicholson River Estate covenant block at $229,500 vacant combined with a build contract of around $440,000 produces a $669,500 total package — inside the FHOG cap and inside the no-LMI threshold. Under the new $1.5 million cap the same buyer still gets the FHOG and the stamp duty saving, but the 5% deposit structure is no longer the binding constraint. What binds first home buyers in the Nicholson corridor is the cash flow between settlement of the land and completion of the build — typically six to nine months — where the FHOG cannot be claimed until the home is completed to lock-up stage. Lenders will require evidence of progress payments during the build period, and builders increasingly offer deposit-bonds instead of cash progress payments to ease the strain. Buyers using a covenant estate block at Nicholson River Estate — where building covenants cover minimum floor areas, façade materials, garage orientation and landscaping standards — should expect to negotiate these build specifications with their builder before signing the land contract, since covenant compliance is enforced at the building approval stage, not at land settlement.
For first home buyers in the Warragul and Traralgon corridors, the picture is simpler. Volume builders are offering turnkey house-and-land packages in the $445,000 to $520,000 range that fall entirely inside both caps, with the FHOG applying at completion. These packages are the cleanest stacking path for first home buyers in 2026 — no covenant negotiation, no separate land-and-build loan structure, and the stamp duty saving can be applied directly to the deposit gap.
Practical playbook for 2026 Gippsland first home buyers
- Confirm you sit inside the FHOG threshold if you want the $10,000. This requires a new build or substantial renovation valued up to $750,000. Established homes inside the regional Vic 5% scheme cap will not attract the FHOG.
- Use the $650,000 no-LMI threshold as the real ceiling, not the $1.5 million scheme cap. Above $650,000, the borrowing cost jumps because LMI returns.
- Pre-validate the deposit-bonds and progress payment structure with your builder if buying covenant land in Nicholson or similar estates, since covenant compliance is enforced at build stage and progress payments cannot be deferred.
- Stack the FHOG and the stamp duty saving by structuring the contract as a single new-build purchase where possible — both apply at the same contract.
- Apply for the 5% Deposit Scheme early in the financial year, because while place limits are uncapped, individual lender allocations still operate on a rolling basis and the major lenders allocate differently each quarter.
The Gippsland first home buyer market in 2026 is more generous on paper than at any point in the scheme’s history, but the practical ceiling for the full stack of benefits remains around $650,000. Inside that ceiling, the math now works for buyers who could not have entered the market twelve months ago — and that is the structural shift that is being absorbed across Warragul, Traralgon, Sale and the East Gippsland corridor in 2026.
Related Coverage
- First Home Buyer Gippsland 2026: $10K Grant, 5% Deposit Scheme & Where to Buy Under $500K
- First Home Buyers in Gippsland: Your 2026 Entry-Point Guide
- Nicholson 3882 Has Two Estates Now — And They Sell Different Dreams
- Nicholson 3882 Elevated Blocks: What $700K-$975K Buys You in 2026
- Warragul Property Market 2026: Median House Prices, Suburb Profile & Buyer Guide
- Latrobe-Gippsland Property Just Had Its Best Quarter in Five Years: Why Wellington Is Leading Regional Victoria
- Maffra Property Market 2026: Why This Wellington Shire Town Is Quietly Outperforming
Proudly supported by hello-clarence.com